
The Essentials of Parcel Insurance in 30 Seconds
Package insurance is a form of financial protection that compensates you for the actual value of your goods in the event of loss, theft, or damage during shipping. It becomes essential whenever your packages exceed €200 in value, contain fragile or irreplaceable items, or involve regular shipping volumes.
The average cost of commercial insurance varies depending on the insurer and the nature of the goods being transported. Without this coverage, a claim could cost you several thousand euros in out-of-pocket expenses, whereas insurance transforms this unpredictable risk into a controllable cost.
This guide details the different types of insurance available, explains how claims are processed, compares the options on the market, and helps you choose the best solution based on your business profile.
What is Parcel Insurance?
Parcel insurance is a financial protection policy that covers your goods against three major risks during transit: total loss (the parcel never arrives), theft (partial or total disappearance of the contents), and physical damage (breakage or deterioration that renders the product unusable).
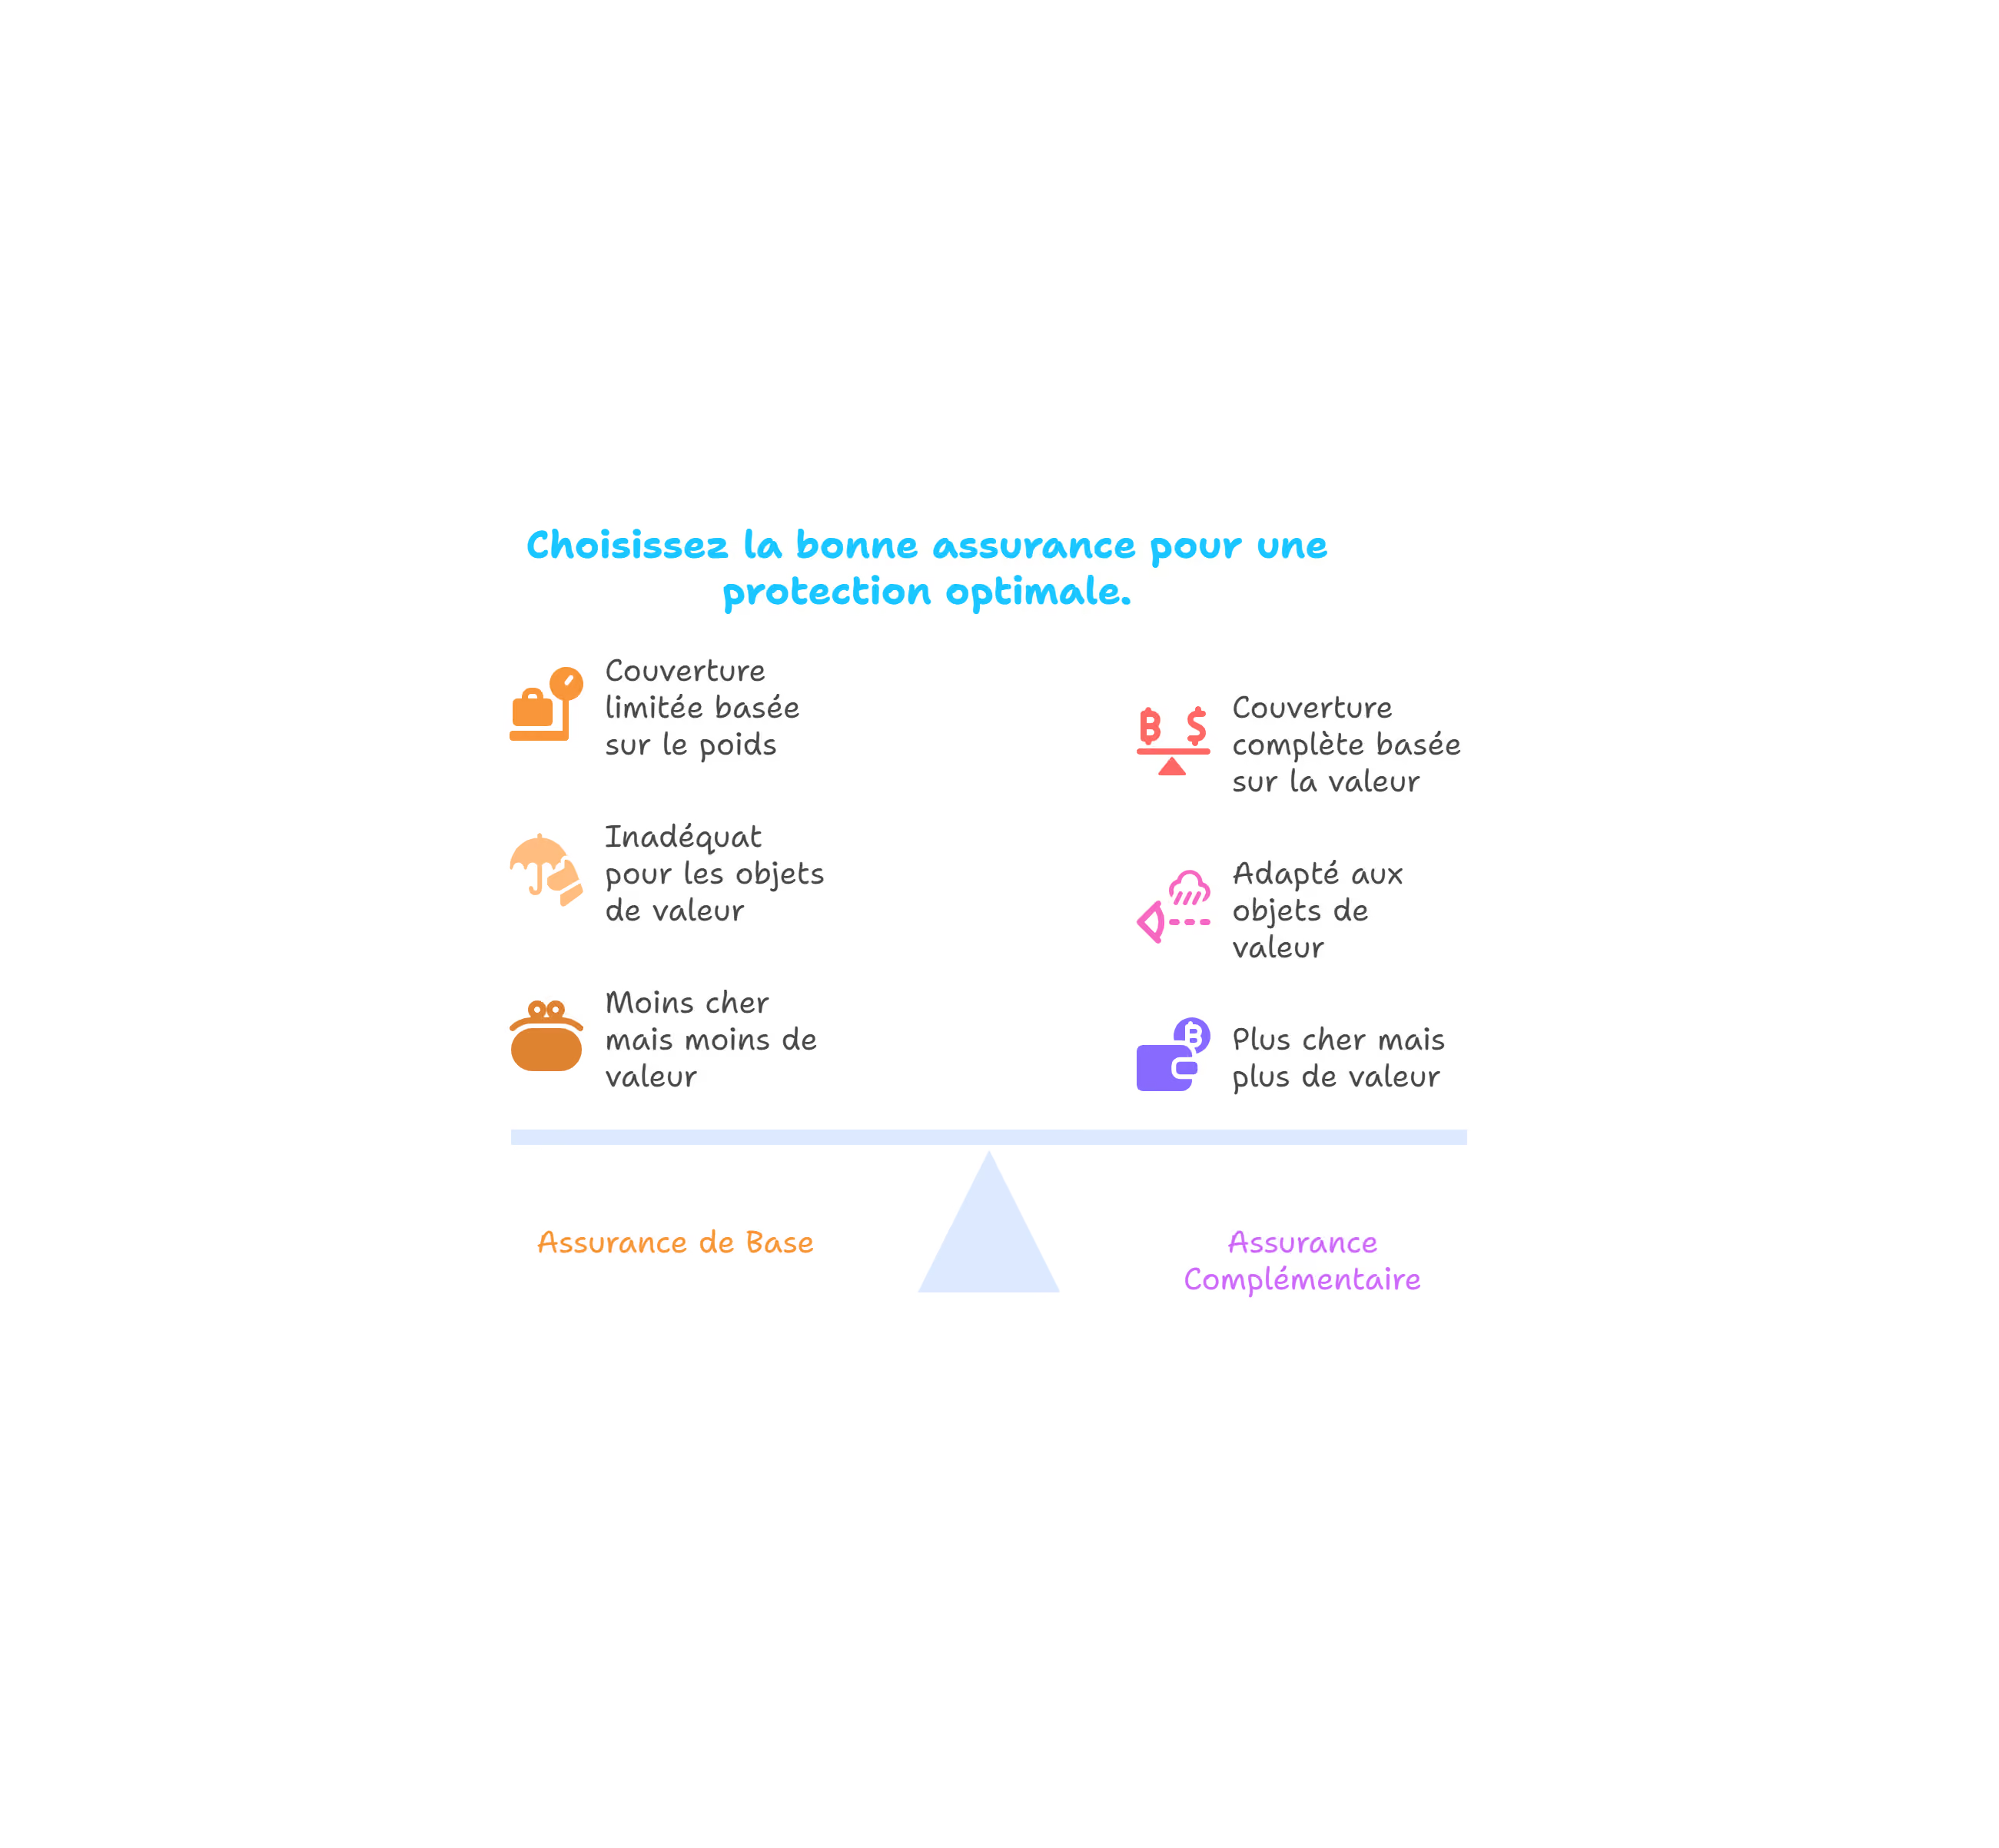
Its sole purpose is to ensure that you are compensated based on the actual declared value of your property, rather than according to a flat rate calculated by weight, as carriers typically do.
The Three Levels of Protection
Carrier Basic Compensation (automatically included)
Calculated by weight, according to the applicable regulations. For international road transport, the CMR Convention caps compensation at 8.33 SDR per kilogram, or approximately 10 € per kilogram. For domestic shipping, each Carrier applies its own rate schedule: Colissimo, for example, pays compensation of €23 per kilogram, while the general standard contract ranges from €20 to €33 per kilogram, generally capped at €1,000 per package (sometimes as low as €600). For a 200-gram smartphone worth €1,200, compensation therefore ranges from €2 to €6.60, depending on the policy. This compensation is negligible for valuable items.
Ad valorem insurance (optional)
You declare the exact value of the item at the time of shipment. In the event of a claim, you will be reimbursed based on this declared value. This is the only real protection for any product with a high value-to-weight ratio. Offered by carriers (for a fee) or by independent specialized insurers.
Comprehensive Insurance (Specific Cases)
Premium coverage that also includes extreme weather events, strikes, and political unrest. Available only for shipments to unstable regions or for highly sensitive goods.
The Regulatory Framework
The principles of package insurance are governed in France and Europe by the CMR Convention (Convention on the Contract for the International Carriage of Goods by Road). This convention sets the basic liability for international road Carrier ation at 8.33 SDRs per kilogram of gross weight missing (Article 23, paragraph 3). The SDR, or Special Drawing Right, is a unit of account used by the International Monetary Fund whose value fluctuates: this Limit currently equates to about ten euros per kilogram. Only the value in SDRs is considered valid. The CMR applies only to international road transport. For domestic transport, national model contracts and the general terms and conditions of each Carrier apply, with different rate schedules.
This legal limitation explains why the basic compensation is negligible for most modern products: it was designed for the transport of heavy goods with low unit value, not for e-commerce involving electronics, fashion, or luxury goods.
Why Package Insurance Is Strategic
Protect Your Cash Flow
An uninsured loss results in a threefold cost that most shippers underestimate:
Direct cost: Purchase price of the merchandise
Reshipment cost: New product + new shipping fees to satisfy the customer
Time cost: 45 to 90 minutes of customer service handling per case Dispute
Real-world example: A product sold for €350 with a purchase cost of €180 results in a direct loss of €188 (product + initial shipping), plus €188 in return shipping costs and approximately €38 in customer service time (average hourly rate). Total impact: €414 for a sale that was supposed to generate a €170 profit margin.
Delays in compensation payments exacerbate the impact on cash flow. According to industry data, traditional carriers take an average of 60 to 90 days to process a claim and pay compensation. During that time, your cash flow bears the loss without compensation.
According to the 2024 Sendcloud study on delivery claims, the annual cost of uninsured claims for French retailers exceeds 2.3 billion euros.
Protecting Profit Margins and Reputation
The psychological reality is inescapable: a customer whose package is lost or damaged never blames the shipping company. They blame you. In their mind, you’re the one who chose the wrong service provider, packed the product poorly, or mishandled their order.
According to the 2024 OpinionWay study on e-commerce satisfaction:
- 66% of customers whose packages are lost will never order from the same company again retailer
- 43% leave a public negative review
- 34% do not return even if they are reimbursed
The average customer acquisition cost in the French e-commerce sector (source: Fevad 2025) ranges from €35 to €80, depending on the industry. A single poorly handled complaint therefore represents a potential loss of €450 to €900 per dissatisfied customer (CAC + lost CLV).
With insurance that allows for quick reshipment or reimbursement, you can turn a mishap into proof of your reliability.
Anticipating Structural Risks
Certain times of year or situations drastically increase the likelihood of incidents. Sorting centers become overwhelmed during peak season (Black Friday, Christmas), and less experienced seasonal workers make more handling errors. Take the initiative and check out our guide to preparing for the 2026–2027 peak season.
The 4 Types of Package Insurance
1. Basic Compensation (Included Automatically)
How It Works: All carriers include, by default, a minimum liability calculated based on the package's weight. In France and the EU, this compensation is governed by the CMR Convention, which sets the limit.
Table: Actual Basic Compensation
Verdict: This basic coverage is unsuitable for 95% of modern e-commerce products. It is only acceptable for goods with a very low value-to-weight ratio (used books, basic clothing sold in large volumes).
2. Ad Valorem Insurance Offered by Carriers
How it works: Carriers (La Poste/Colissimo, Chronopost, DHL, UPS, FedEx) offer an optional paid service that allows you to declare the actual value of your item. In the event of a claim, you will be compensated based on this declared value.
Variable Features: Rates, limits, and exclusions vary significantly from one Carrier to another. For detailed analyses by Carrier, see our specialized guides:
- Colissimo Insurance Analysis
- Insurance Analysis Chronopost
- DHL Insurance Analysis
- UPS Insurance Analysis
- FedEx Insurance Analysis
Limits currents:
- Colissimo: €1,000 (individuals), €5,000 (businesses with a contract)
- Chronopost : €20,000
- DHL/UPS/FedEx: €40,000–50,000
Compensation Processing Times: According to customer feedback from the industry, carriers take an average of 60 to 90 days to process a complete claim and pay the compensation.
Common exclusions:
- Jewelry and precious metals: Often excluded or capped at between €1,000 and €5,000
- Works of Art: Excluded or Subject to Very Strict Conditions
- Refurbished Products: Varying Acceptance Criteria
- Luxury watches: Generally excluded above certain amounts
3. Independent Specialized Insurance
How it works: Specialized insurers offer coverage that is separate from Carrier. You purchase the insurance separately, then ship your package through the Carrier of your choice.
Structural advantages:
- Total flexibility: Switch to a different Carrier plan based on your needs without changing insurers
- Limits High: Coverage of up to €100,000 per package, generally
- Extended Coverage: Acceptance of Products Often Excluded by Carriers
- Simplified process: Centralized management regardless of the Carrier
- Quick turnaround: Compensation within 48–72 hours after the claim is approved
For a detailed comparison of the options available on the market, check out our 2026 package insurance comparison.
4. Secure Shipping with Built-in Insurance
How it works: For very high-value goods (>€100,000), specialized services (Brink's, Malca-Amit) combine armored vehicles, armed guards, secure routes, and comprehensive insurance with no Limit.
Sectors involved: High-end jewelry, major works of art, precious metals, and strategic industrial prototypes.
To learn more about this topic, see our guide to cargo insurance.
How to Choose the Right Package Insurance
The optimal choice depends on four key criteria.
Criterion 1: Average Value of Your Shipments
Decision Matrix by Category
Less than €50: The flat-rate compensation may be sufficient, but check the value-to-weight ratio. A €40 item weighing 200 g is covered up to only €4.60.
€50 to €200: Ad valorem insurance is recommended for fragile items or items with a high value-to-weight ratio.
€200 to €5,000: Ad valorem insurance is strongly recommended. An uninsured loss in this price range can wipe out the profit margin on many sales.
Over 5,000€: Specialized insurance with high caps is required. Carriers generally cap or exclude these amounts.
Criterion 2: Monthly Shipment Volume
Fewer than 50 parcels per month: Integrated carrier insurance is acceptable for its simplicity (a single invoice).
50 to 500 packages/month: Ideal range for specialized insurers. Automation available through CMS integrations (Shopify, PrestaShop, WooCommerce).
More than 500 packages per month: Recommended specialized insurer with advanced API integrations for full automation.
Criterion 3: Nature of the Shipped Products
Certain products are systematically excluded or severely restricted by carriers' insurance policies.
For the luxury sector, see our watch and jewelry insurance guide.
Criterion 4: Use of Multiple Carriers
Just one delivery company: The built-in carrier insurance feature may be all you need.
Multiple Carriers: Decoupled insurance is becoming essential to avoid having to juggle multiple insurance policies with separate processes and to ensure consistent coverage.
Process: From Enrollment to Claims Payment
Before the Expedition
Declare the exact value: The value to be declared is the actual market value of the item, which can be substantiated by an invoice. Never underreport the value: compensation will be partial. Never overreport the value: this constitutes fraud and will result in a total denial.
Special cases:
- E-commerce Sales: Sales Price (Including Tax)
- B2B Shipments: Purchase Value Excluding VAT + margin
- Reason: Resale value recorded
- Gift: Equivalent market value
Follow packaging standards: Many claims are denied due to “non-compliant packaging.” Common requirements:
- New or reused box in perfect condition
- Double-wall corrugated packaging for fragile items or items costing more than €200
- Adequate clearance (at least 5 cm on all sides)
- Reinforced tape, at least 50 mm wide
- Complete anonymity (no visible markings or values)
Preserve the evidence:
- Shipping Label with Tracking Number
- Invoice or proof of purchase
- Product photos before packaging (6 sides)
- Photos of a sealed package
If You Have a Problem
Reporting deadlines:
- Damaged Package: 48 Hours After Delivery
- Lost Package: 7 Days Without a Tracking Update
- Delivery Not Received: 72 hours after the specified date
Required documents:
- Product Invoice
- Shipping Slip
- Photos of damage (if broken) or proof of non-delivery
- For amounts over €1,000: Filing a police report + proof of identity
Conclusion
Parcel insurance transforms an unpredictable financial risk into a manageable cost. The coverage provided by carriers—calculated by weight (from €10 to €33 per kilogram, depending on the plan)—is inadequate for most modern products. Ad valorem insurance, based on actual value, fully protects your cash flow and your reputation.
The choice between a carrier insurance policy and a specialized insurer depends on your sales volume, the nature of your products, and your need for flexibility. Independent insurers generally offer higher caps, shorter claims settlement times, and coverage extended to products that are often excluded.
Sources: